


This week on Eximius Echo, we’re unpacking the next structural shift in climate tech: the move from carbon reporting tools to AI-driven operating systems.
For years, climate software focused on measurement - counting tonnes, building dashboards, exporting reports. That layer mattered. But as grids tighten, renewables hybridise with storage, and policy becomes more granular, the real bottleneck is no longer reporting. It is decision-making under complexity.
AI is beginning to change that foundation - not by generating more insights, but by turning physics, policy, and capital constraints into optimised actions. The value is shifting from dashboards to decision infrastructure.
If you’re new here, Eximius is a pre-seed VC fund backing bold ideas in FinTech, ConsumerTech, and Enterprise AI. Through this newsletter, we explore the structural shifts shaping tomorrow’s markets.
Let’s dive in.
For most of the last decade, climate software looked like reporting. Count the tonnes. Build a dashboard. Export a PDF. Route it to a sustainability team that sits somewhere between brand and compliance.
That wave mattered, and it built real businesses. But it also trained the market to believe that “climate tech” is mostly measurement plus storytelling.
What we are seeing now feels like infrastructure. The transition is getting physical, regulated, and operational. When grids move to tighter settlement windows, when renewables become hybrids with storage, and when policy varies not just by country but by state, the bottleneck stops being intent and becomes decision-making under complexity.
This is where AI becomes useful, not as a climate chatbot, but as a layer that makes messy workflows legible. The most interesting Climate x AI companies are building decision engines for high-stakes moments: how a project is sized, how a PPA is structured, how an asset is dispatched, how penalties are avoided, and how value is stacked across multiple revenue streams.
The opportunity here is not one product. It is a shift in what the climate stack even means.
The Excel Cliff
Most climate infrastructure decisions still start in spreadsheets. Excel is the default because it is flexible and trusted.
But we are hitting an Excel cliff.
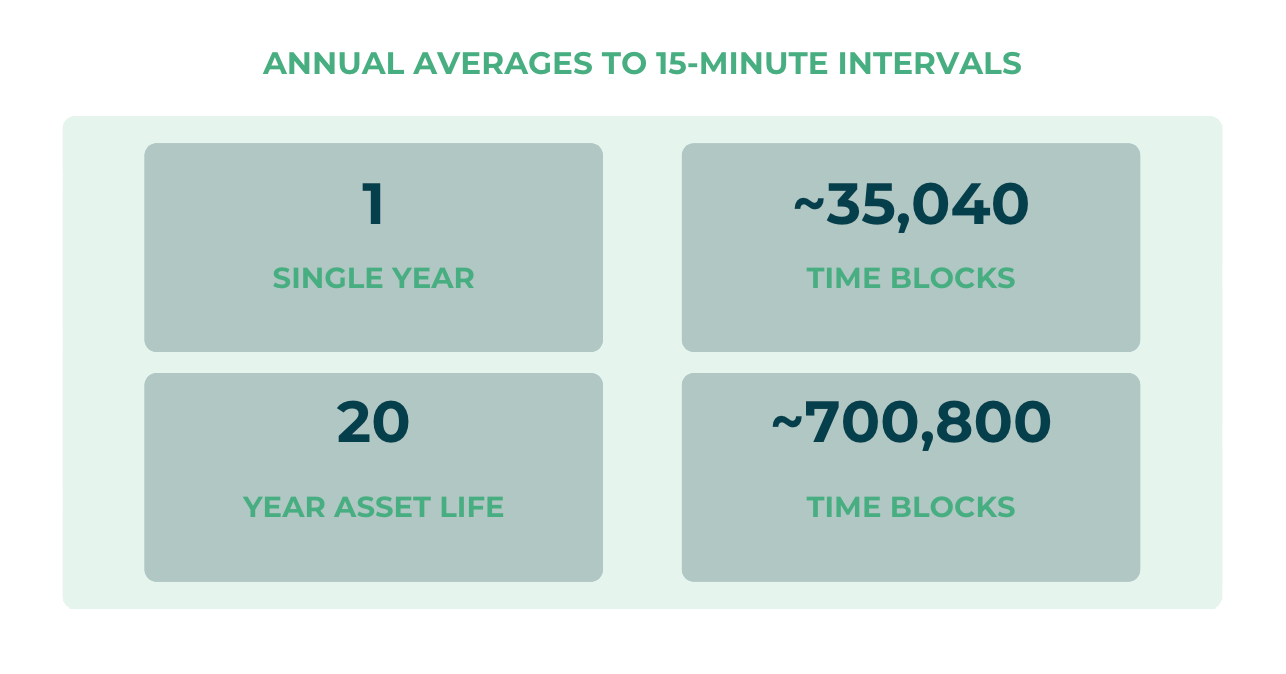
Move from annual averages to 15-minute intervals, and a single year becomes ~35,040 time blocks. A 20-year asset life becomes ~700,800 blocks. Now add multiple assets (solar, wind, batteries), degradation curves, curtailment assumptions, grid constraints, and state-specific charges. Add financing (cashflow, DSCR), contractual clauses (guarantees, penalties), and scenarios (variants to shortlist, then finalise terms). At that point, you do not have a “model”. You have a brittle software product living inside a file, held together by human discipline.
The real problem is not compute. It is governance. When a model becomes too complex to audit, teams simplify assumptions until the model fits the tool. Value leaks quietly. Or decisions start depending on who built the spreadsheet, not what the world actually looks like.
A large share of climate value creation over the next decade will come from preventing that leak.
From Carbon Math to Asset Math
Climate software is moving from accounting to operations: from reporting what happened to deciding what to do next, and what it will do to EBITDA, risk, and compliance.
Renewables are a clean example. Early solar was relatively forgiving. Planning was simpler, grid rules were looser, and contracts tolerated smoothing. The new era is less forgiving. Hybrids and storage introduce control variables. Penalty regimes tighten. Merchant markets and day-ahead participation introduce price signals. Suddenly, the difference between “good” and “great” is not branding. It is math and execution.
In many markets, regulators are compressing the feedback loop. Shorter settlement windows mean errors surface quickly and get priced quickly. Forecasting quality becomes a financial variable, and deviations become a line item.
That is why “asset math” is becoming core. You need software that understands the physics of the asset, the economics of the contract, and the rules of the grid, all at once.
The New Stack: Physics, Policy & Optimisation
Climate is one of the few verticals where physics and policy shape the product at the same time.
Physics is non-negotiable. Solar yields, wind intermittency, battery round-trip efficiency, cycle life, C-rate constraints, and degradation are real. Policy is equally non-negotiable. Grid charges, banking rules, wheeling, net metering, open access, forecasting compliance, deviation penalties, time-of-day tariffs. The same project in two jurisdictions can behave like two different businesses.
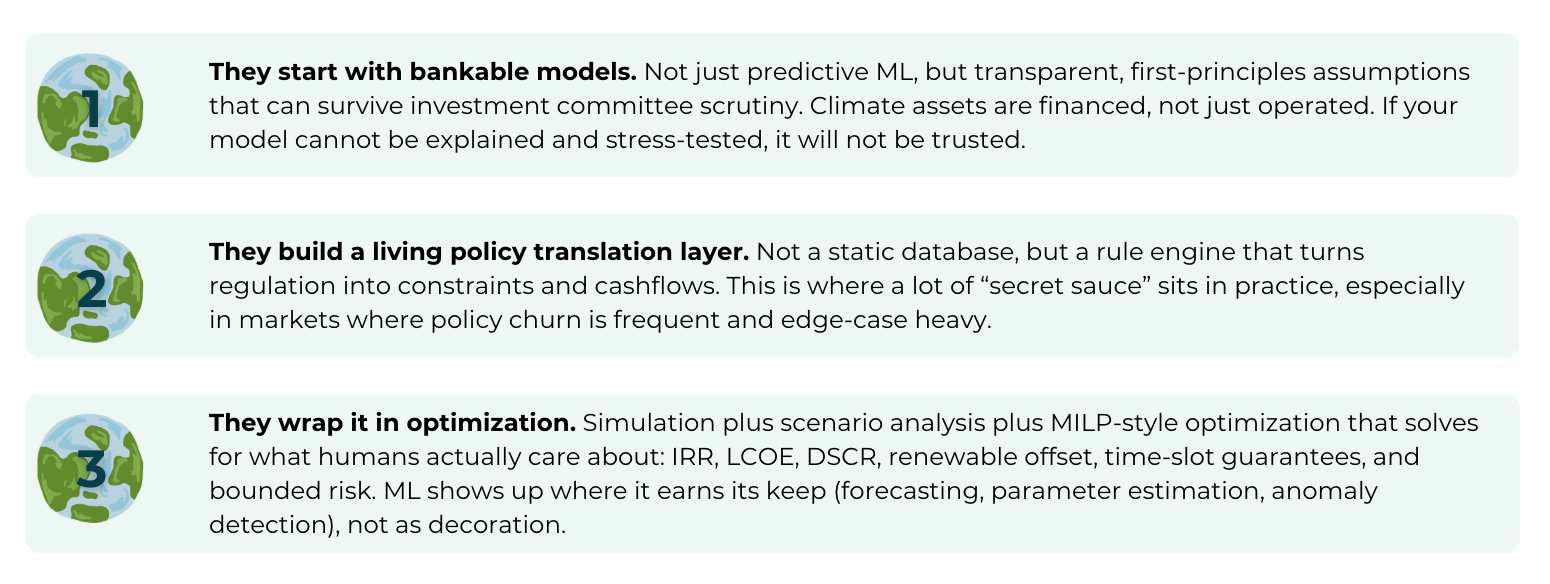
The strongest platforms stitch three layers together:
Planning is the Wedge, Operations is the Compounding Loop
In infrastructure, planning is often the easiest wedge because the pain is immediate and the ROI is legible. It is where projects are designed, bids are won, and contracts are shaped.
Small improvements here can be surprisingly valuable. Developers routinely add buffers to be safe, especially in hybrid and storage-heavy systems. If software helps reduce that buffer even slightly, the capex impact is meaningful. Saving 1 MW of unnecessary capacity on a 30 MW project is not a feature. It is money.
But planning alone is rarely the endgame.
Operations is where stickiness compounds. Once an asset is live, the problems become continuous:
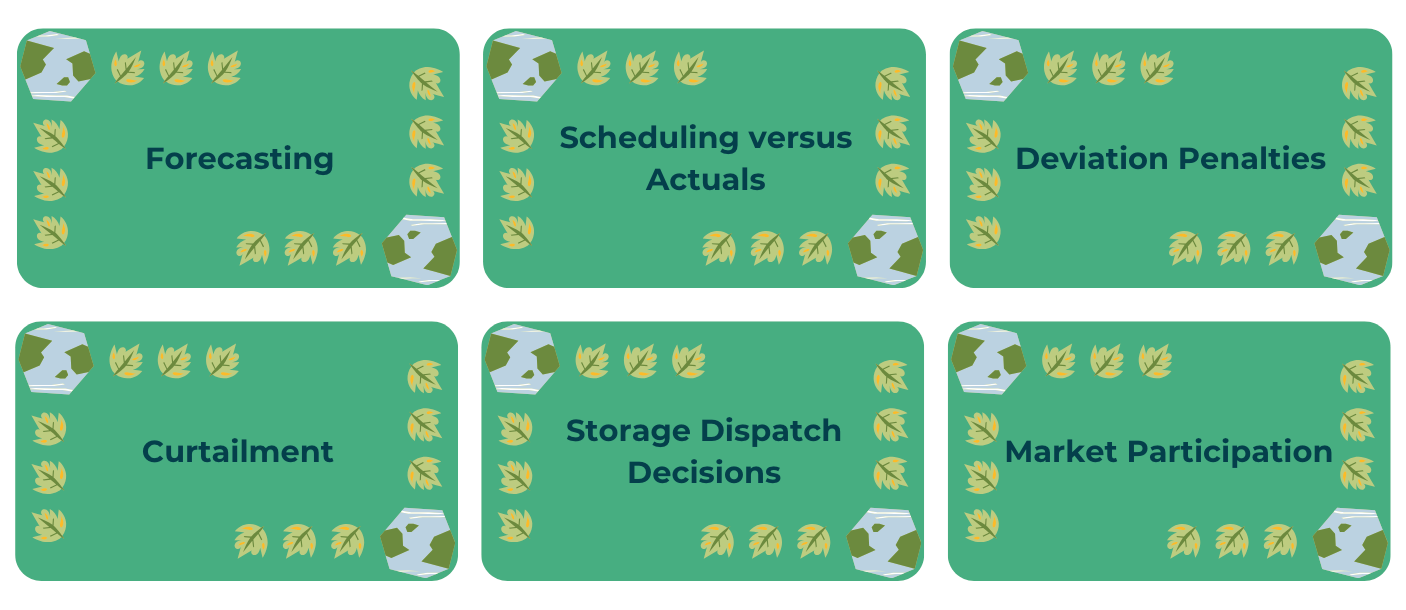
The most compelling long-term arc is “an energy desk in software”. A system that understands the asset, the grid, and the contract, and can recommend (and over time automate) actions that protect and improve EBITDA.
Batteries make this especially interesting because they convert uncertainty into control. If you are long, charge. If you are short, discharge. If prices are low, charge from the grid (where allowed). If penalties tighten, optimise for compliance. Value stacking stops being a slide. It becomes a dispatch policy.
Procurement will look like FinTech, Not Consulting
Another theme that keeps resurfacing is procurement, especially for corporates sourcing renewable energy.
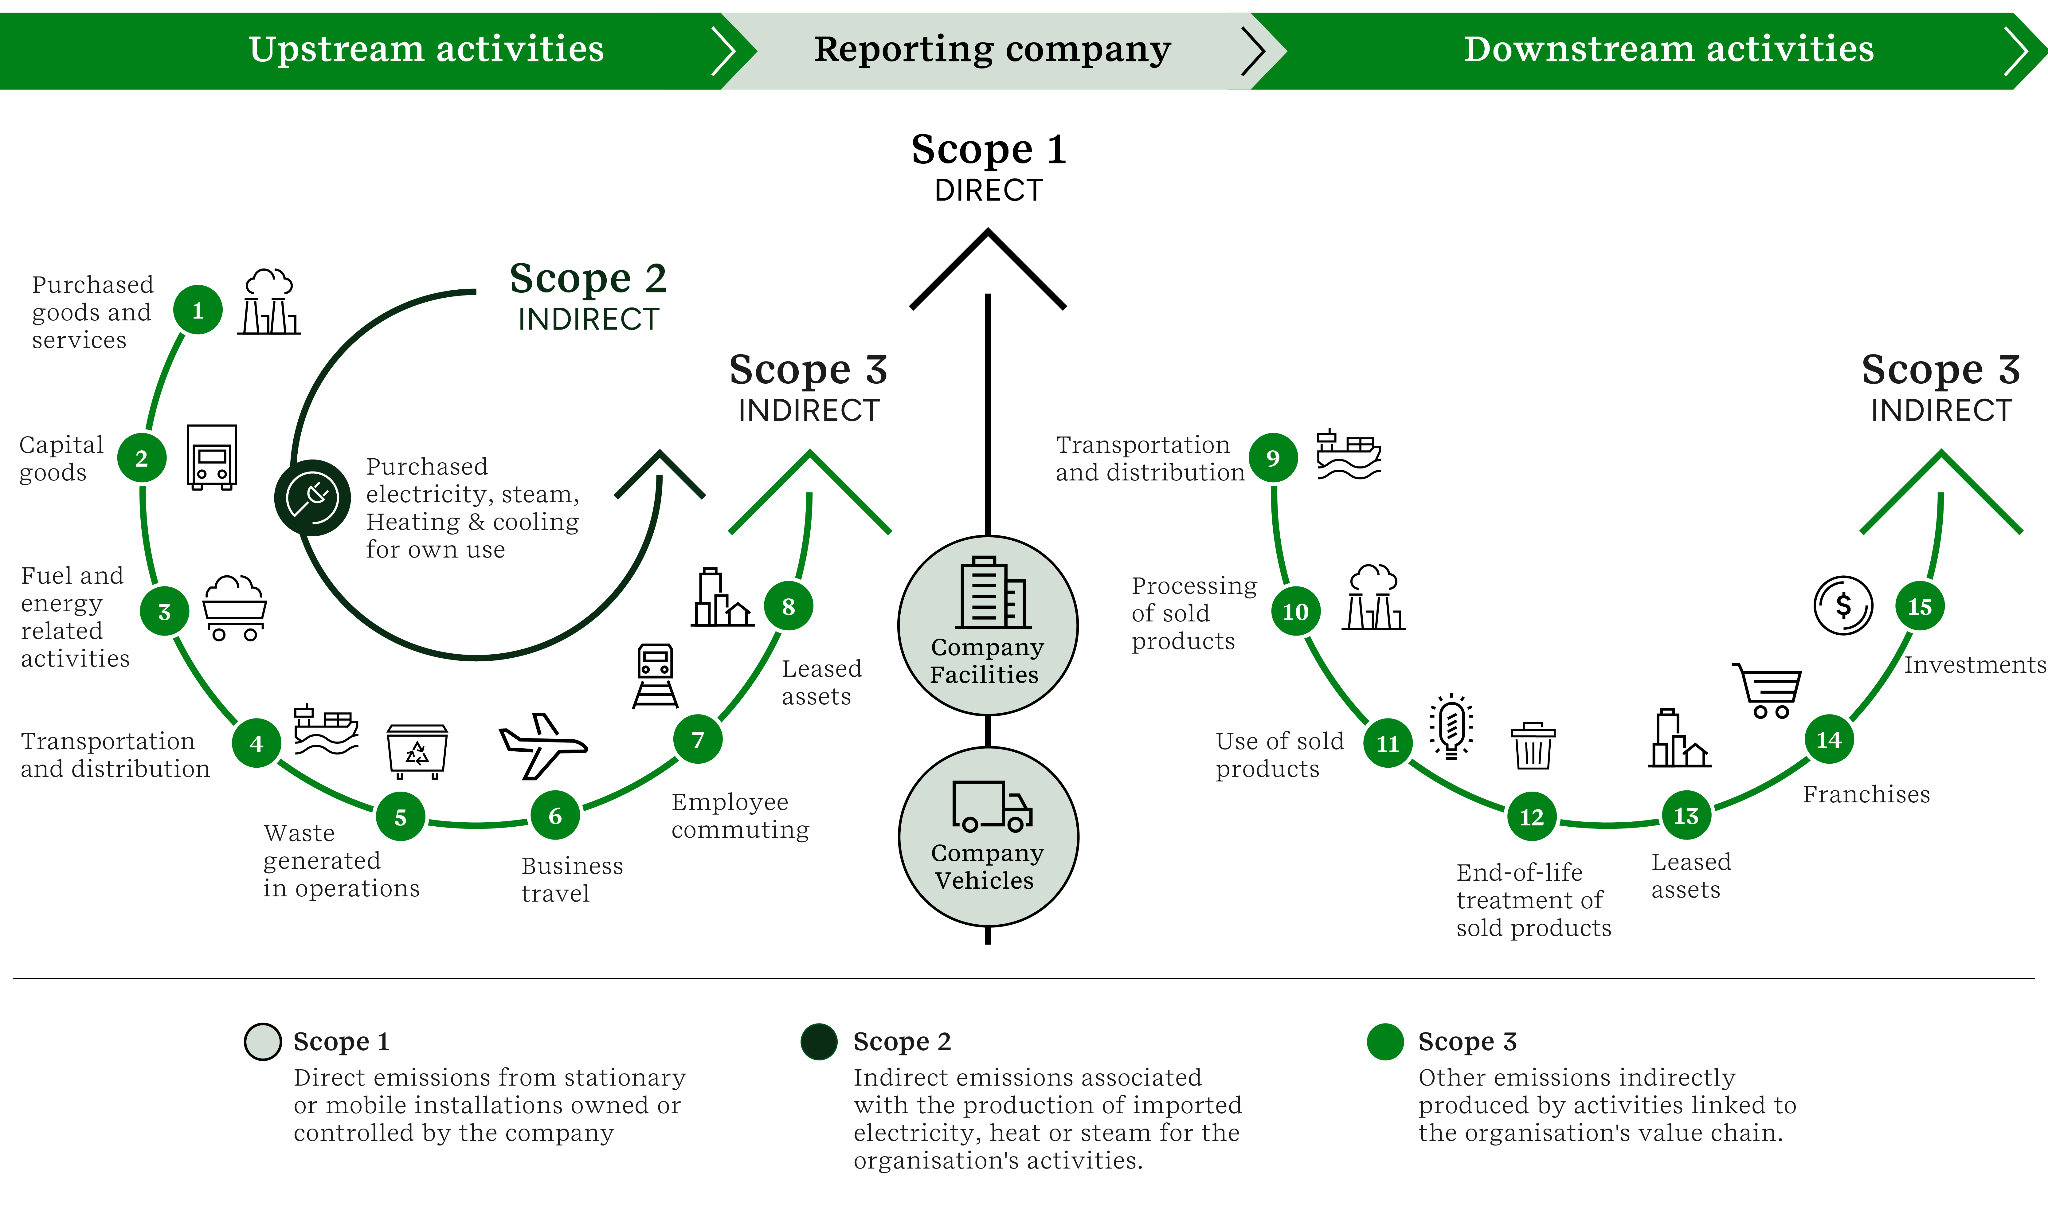
A similar dynamic is emerging in Scope 3 programs. Large companies want to help suppliers decarbonise, but last-mile work (tariffs, load profiles, payback math) still lives in spreadsheets and consultants. Standardising that decision surface can beat another emissions report.
Software will not remove relationships, but it can standardise the decision surface.
A good platform does not just list developers. It translates the buyer’s load curve into requirements, normalises submissions into comparable scenarios, and helps the buyer choose based on landed cost, reliability, and risk. Commercially, this often leads to blended models: low-cost planning for the buyer, and a success fee from the winning counterparty aligned with deal size. You see commissions that resemble the offline market (often ~0.75% to 1.5%), but with better transparency and repeatability.
The nuance is that procurement itself is a commodity. Developers win on cost of capital, execution ability, and risk appetite. So defensibility comes from trust and underwriting: delivery history, performance variability, counterparty strength, and sometimes payment default risk. Climate procurement marketplaces will behave more like fintech than e-commerce. The scoring and risk layer will matter as much as the listing layer.
Where Moats Actually Form
“Data moat” is an overused phrase in climate. The durable moats we see tend to be more specific:
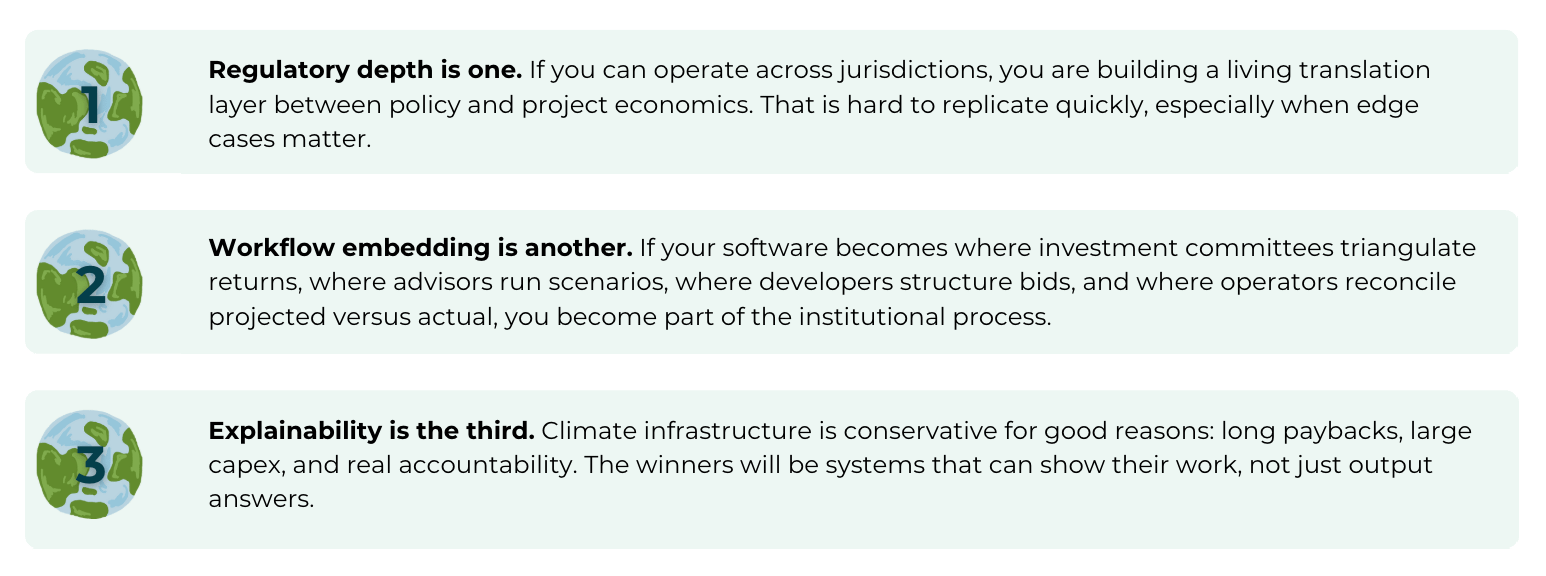
And there is a distribution moat: selling through capital. If you can land inside platforms that sit above many assets (portfolio owners, lenders, insurers), you can scale faster than selling project-by-project.
What this means for Founders & Investors
This category is entering a phase where planning and operations start blending. The same engine that sizes an asset can later run it. The same policy layer that informs capex decisions can later drive compliance and dispatch. The same optimisation framework that helps win a tender can later protect margins in the field.
Sequencing is the hard part. Planning is a great wedge, but it can trap you in project services if you do not convert to recurring workflows. Operations is sticky, but integrations can slow early GTM. Procurement is large, but commoditises if you do not own the risk layer.
As early-stage investors, we have found it useful to stay concrete. We care less about “AI for climate” and more about whether the product provably reduces time-to-decision, whether it is credible to both engineers and finance teams, whether policy is treated as product (not a feature), and whether there is a path from insights to actions.
Closing Thought
The climate transition is often described as an energy transformation. True, but incomplete.
It is also a decision transformation. The world is not short of capex. It is short of trustworthy, repeatable decision-making under constraints.
As complexity rises, the winners will not be the companies that shout “AI” the loudest. They will be the companies that turn messy physics and shifting policy into decisions that feel obvious in hindsight, and then turn those decisions into actions that move real electrons, real money, and real outcomes.
If you’re a founder building in this space, we’d love to chat. Reach out to us at pitches@eximiusvc.com

