


This week on Eximius Echo, we’re breaking down some of the most important signals from our newly launched Pre-seed Investment Playbook 2026.
If you’re new here, Eximius is a pre-seed VC fund backing bold ideas in FinTech, ConsumerTech, and Enterprise AI. Through this newsletter, we explore the structural shifts shaping tomorrow’s markets.
Let’s dive in.
India’s startup ecosystem has entered a new phase. The conversation is no longer only about how much capital is available. It is about what that capital is actually helping founders build.
As some of you may know, we recently launched the Pre-seed Investment Playbook 2026 in collaboration with 1Lattice. The report was built to understand a market we believe is becoming one of the most important layers in Indian venture capital today: pre-seed, not as a loose category of early cheques, but as the stage where company quality, execution discipline, and long-term graduation potential begin to take shape.
Download the full Playbook here: DOWNLOAD
Here are 5 things you should absolutely know about the pre-seed funding and investing landscape in India.
1. PRE-SEED IS NO LONGER A SIDE LANE. IT IS BECOMING THE STRUCTURAL ENTRY POINT.
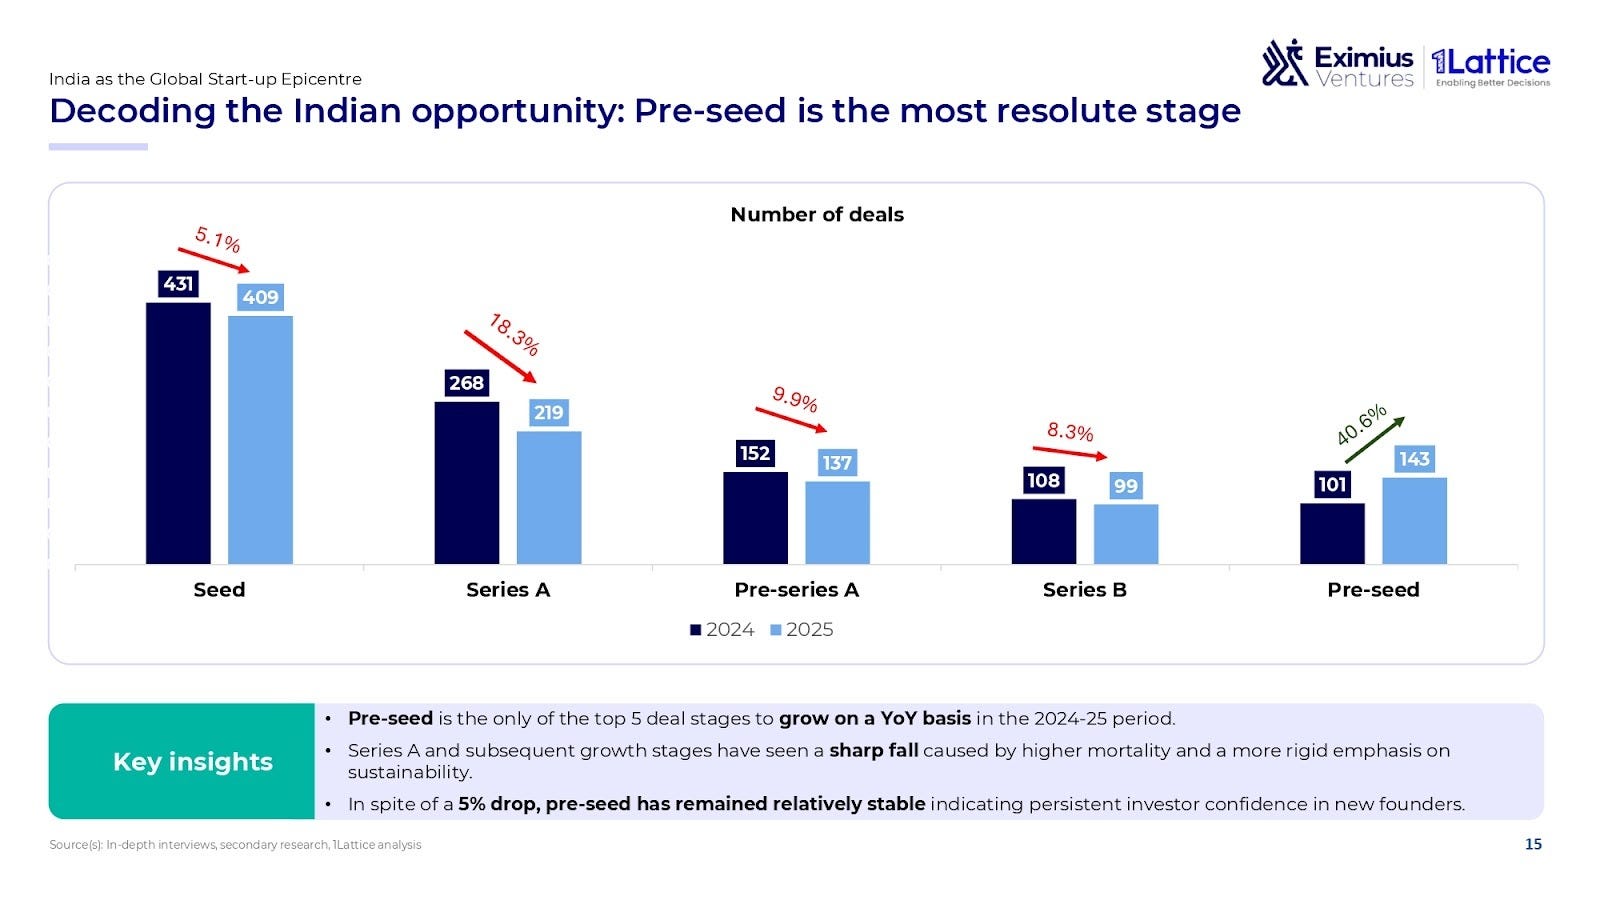
One of the clearest signals from the report is this: pre-seed is the only major funding stage that grew year-on-year in 2024-25. India’s pre-seed ecosystem has also expanded roughly 3X since 2020. In a market where later-stage capital has remained cyclical and more selective, this is a meaningful shift.
This tells us something important. Investors are moving earlier, but with sharper intent. Founders are also approaching this stage with greater seriousness. Pre-seed is increasingly where conviction gets underwritten, not only on the idea, but on the founder, the speed of learning, and the path to building something enduring.
2. INDIA’S CHALLENGE IS NO LONGER CAPITAL ACCESS. IT IS GRADUATION.
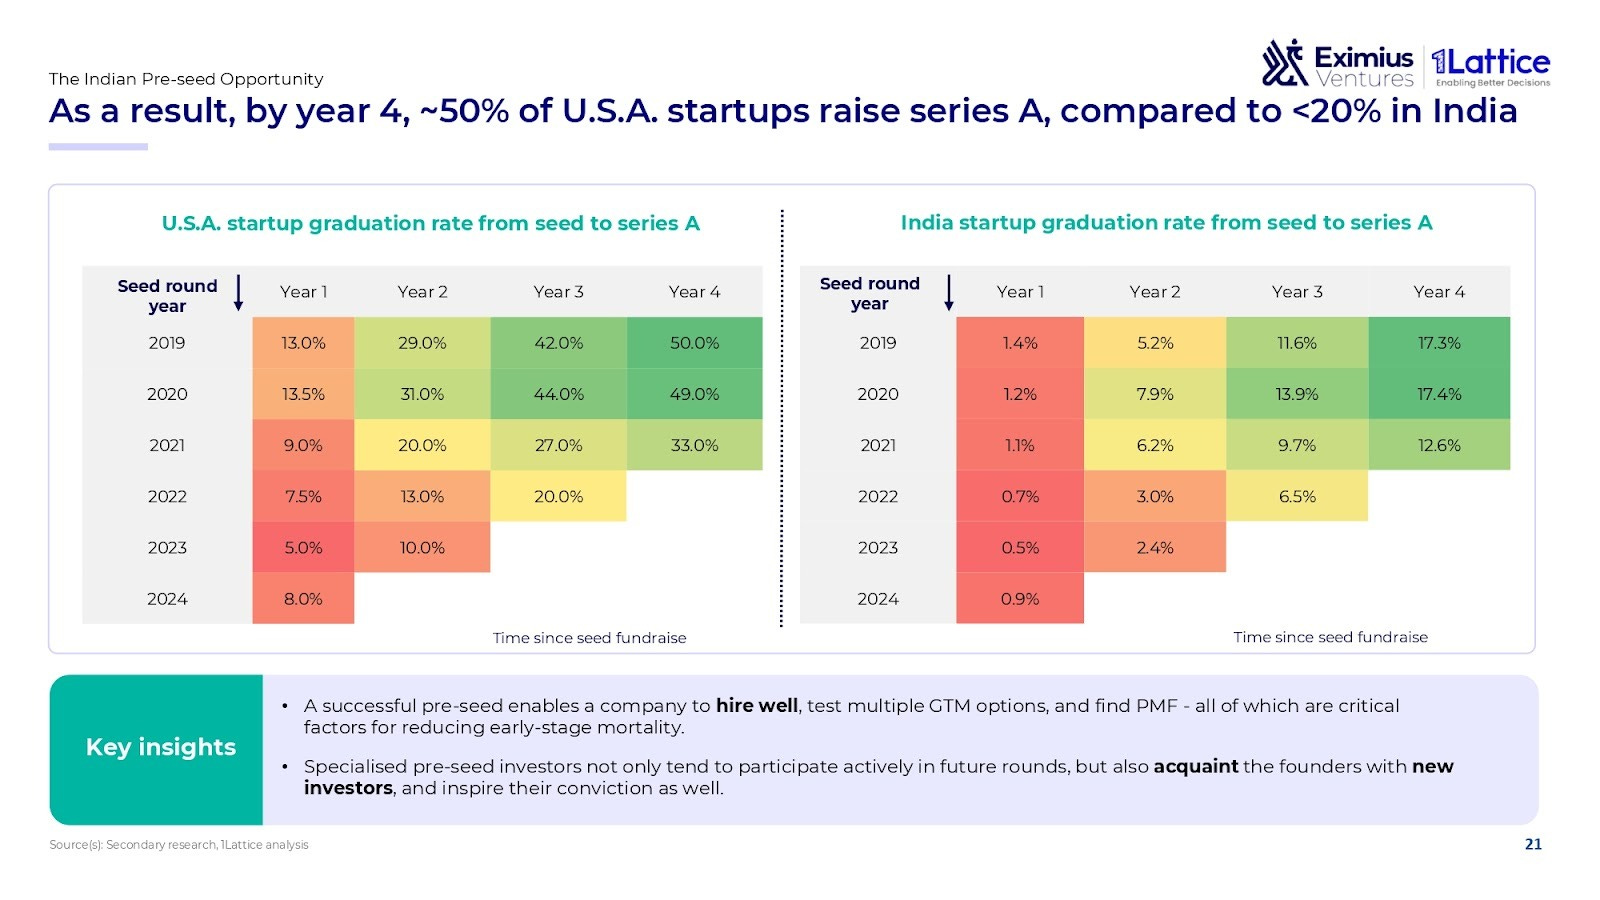
The headline number from the report is hard to ignore: fewer than 20% of Indian startups reach Series A by Year 4. In the U.S., that number is closer to 50%.
That gap captures the real problem. India has expanded its early capital base through angels, syndicates, family offices, micro-VCs, and accelerators. What has not scaled at the same pace is structured support around product-market fit, go-to-market design, early hiring, governance discipline, and downstream fundraising readiness.
This is exactly why pre-seed matters more today. The first cheque is no longer just catalytic capital. It is a filtering-and-enabling layer. It gives founders time, structure, early feedback loops, and the operating support needed to improve their odds of graduating.
3. THE FOUNDER PROFILE IS GETTING STRONGER, AND THE MARKET IS REWARDING IT.
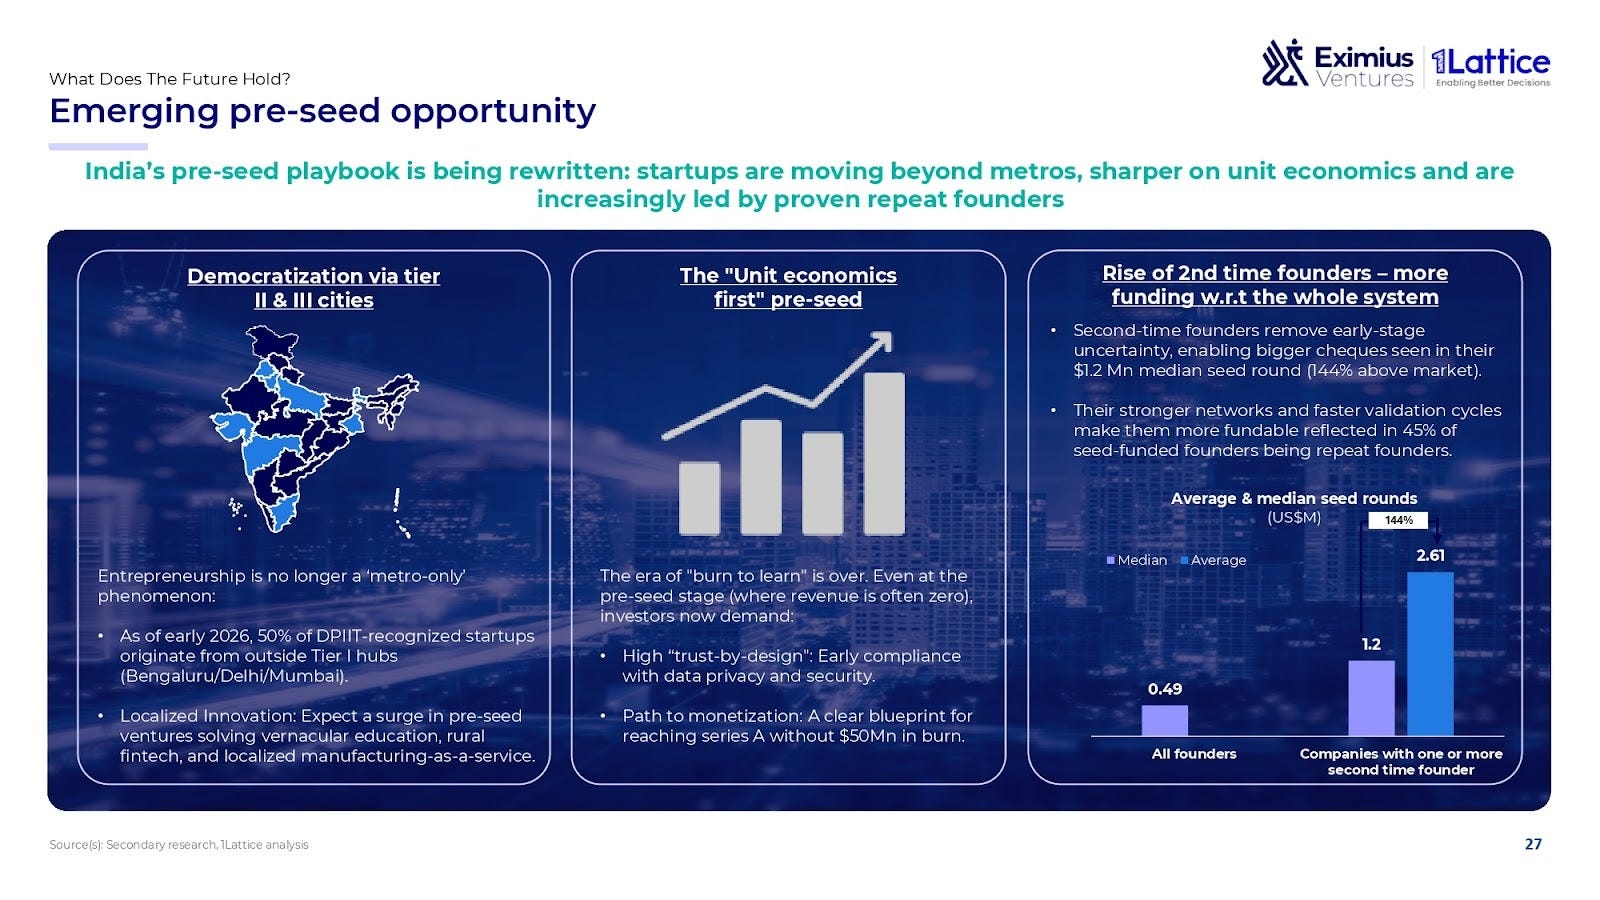
Nearly 45% of seed-funded founders in India are now second-time entrepreneurs. The report also shows that companies with one or more repeat founders raise materially larger seed rounds than the market average.
That shift is changing the texture of the market. Repeat founders bring sharper judgment, stronger networks, faster validation cycles, and often a more disciplined approach to capital. Investors are responding accordingly.
There is also a broader mindset shift underway. The era of “burn first, figure it out later” has clearly faded. Even at the pre-seed stage, founders are being evaluated on clarity of wedge, speed of execution, monetisation potential, and operational readiness. That raises the bar, but it also makes the ecosystem healthier.
4. INDIA’S NEXT STARTUP WAVE IS BROADENING GEOGRAPHICALLY AND DEEPENING INSTITUTIONALLY.
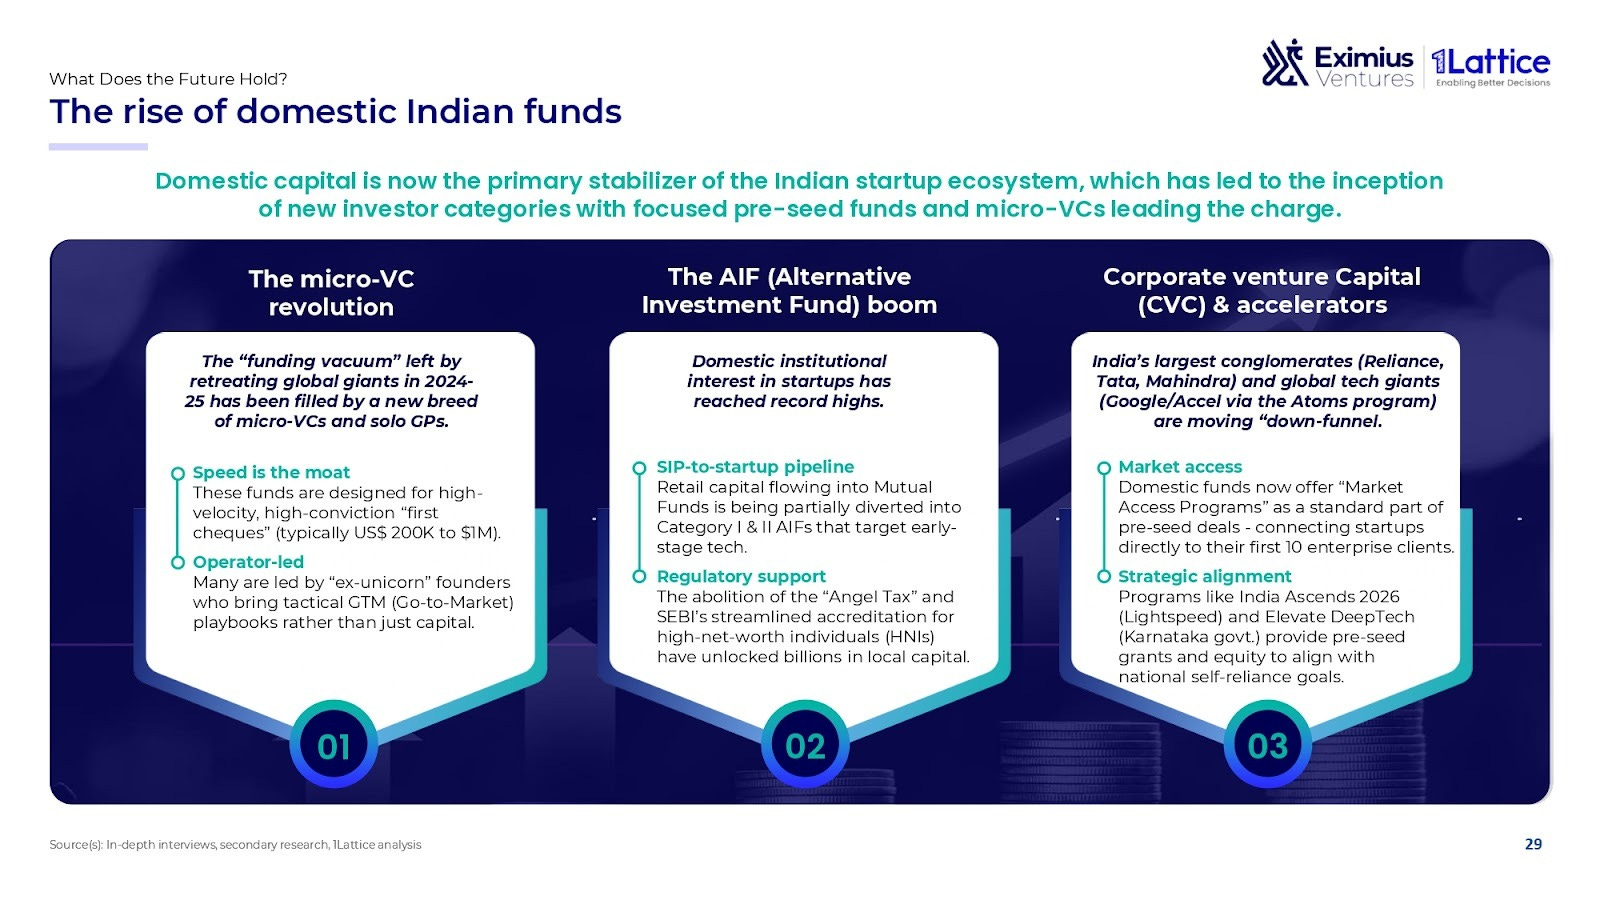
Nearly 50% of DPIIT-recognised startups now originate outside Tier I hubs. That is a major structural shift. Entrepreneurial ambition is spreading beyond Bengaluru, Delhi, and Mumbai, and the next wave of companies is likely to emerge from a much wider set of cities and founder backgrounds.
At the same time, the investor base is evolving quickly. Micro-VC participation has grown nearly 4X since 2021. India now also has 300+ family offices managing approximately US$30B in AUM, with increasing exposure to early-stage opportunities. Between 2020 and 2025, angel investors deployed roughly US$1.7B across more than 3,000 deals.
Domestic capital is steadily becoming the stabiliser of the ecosystem. That matters. It reduces dependence on global liquidity cycles and gives India’s earliest-stage market a more resilient base.
5. THE NEXT WINNERS WILL NOT BE BUILT ON OPTIMISM ALONE. THEY WILL BE BUILT ON EXECUTION DEPTH.
The report points toward a future shaped by applied AI infrastructure, embedded finance, climate and mobility, space and defence tech, healthtech rails, and commerce and logistics infrastructure. These are large, structurally important categories. They are also categories where execution quality matters early.
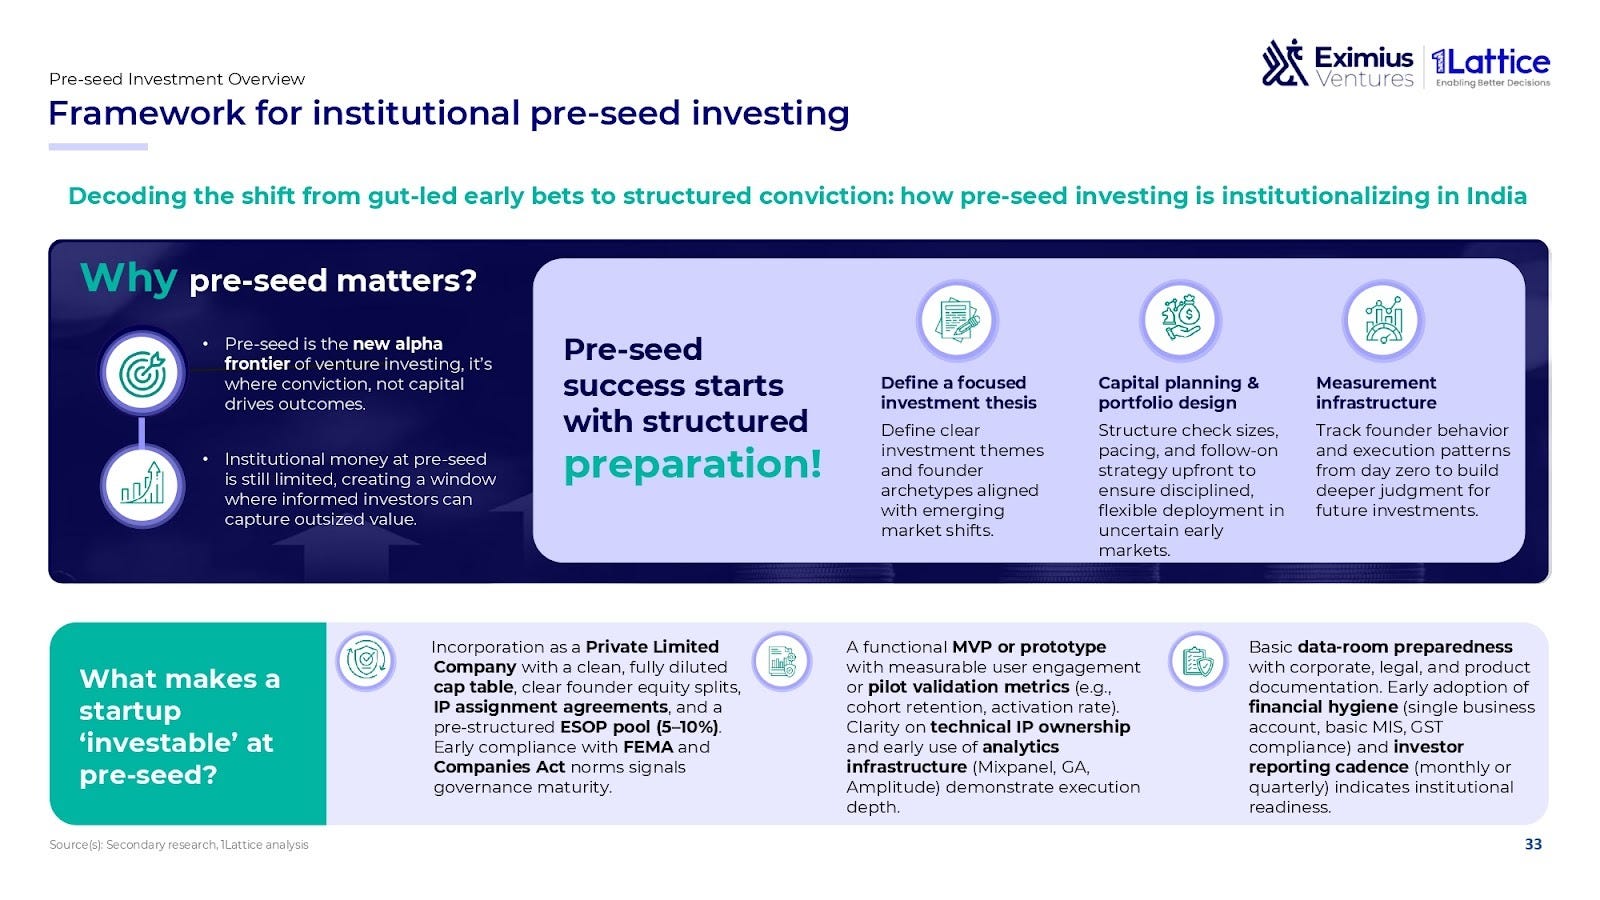
That is why “investable” at pre-seed is being redefined. Clean cap tables, ESOP planning, compliance hygiene, MVP or pilot validation, analytics infrastructure, and basic data-room readiness are no longer nice-to-haves. They are signals of institutional readiness.
For founders, this means choosing pre-seed partners who can do more than wire money. For investors, it means moving from intuition-led early bets to more structured conviction. For the ecosystem, it means recognising that the hardest work in venture often begins before traction becomes visible.
India has already built scale. The next chapter will be shaped by how well it builds from zero to one.
Over the last 1 year, we’ve invested in 10 companies. Over the next 1 year, we plan to invest in 10 more.
If you’re building for the future from India, for India and the world, across ConsumerTech, FinTech, or Enterprise AI, write to us at pitches@eximiusvc.com. We’d love to hear what you’re building.
